FLORIDA PANHANDLE CLAIMS SPECIALIST
Recover the Settlement
You Rightfully Deserve
Insurers consistently lowball storm and hurricane damage across Northwest Florida. Our licensed adjusters re-evaluate your file with NO upfront fees: you pay strictly $0 unless we recover more money form your claim.
NO Upfront Fees · No Fee Unless Recovery

1. Strategic Claim Delay
Insurers stretch response windows across statutory 90-day deadlines, cycling through desk adjusters while commercial mortgages and emergency stabilization costs mount against you.
2. Categorical Exclusion
Field inspectors systematically label catastrophic wind uplift and envelope failure as uninsurable 'wear and tear' or 'gradual moisture intrusion' to shield the carrier from primary indemnity.
3. Algorithmic Underpayment
Standard software templates apply deflated pre-storm baseline pricing, omitting regional subcontractor surge rates, Florida Building Code upgrades, and required structural re-engineering.
THE CARRIER PLAYBOOK EXPOSED
Stop Leaving Money
On The Table
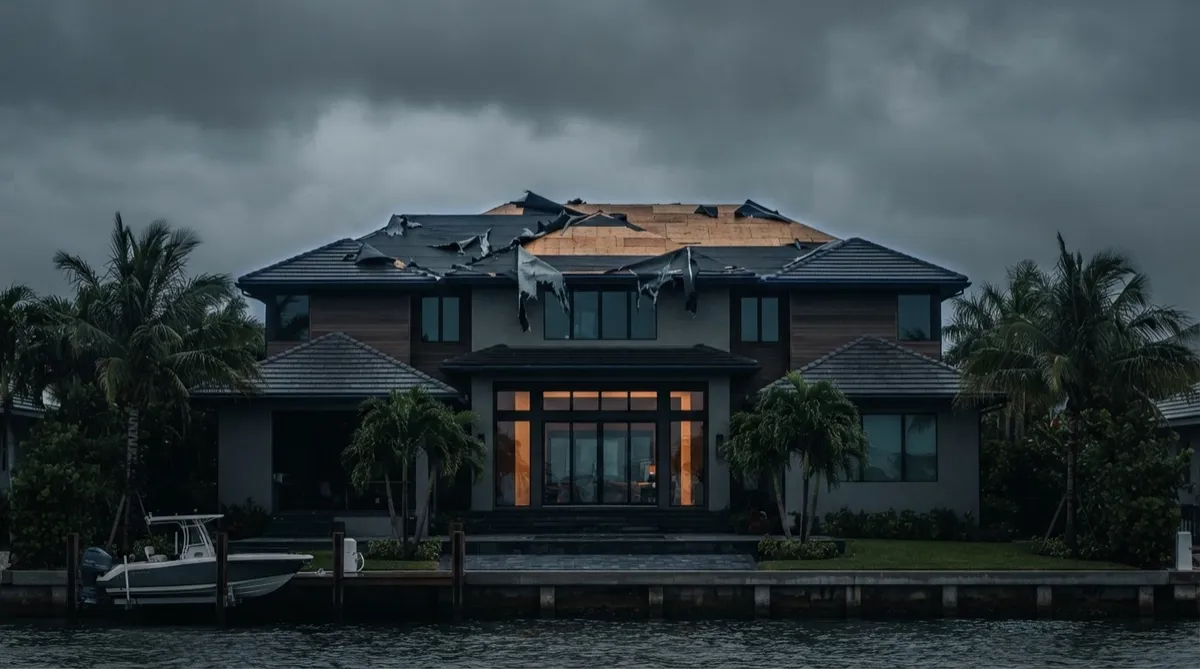
Following severe storm and hurricane incidents across the Panhandle, carrier adjusters arrive on site with one structural objective: minimize claim exposure. Initial scope summaries routinely bypass hidden roof shear, saturated insulation cavities, and mandated local code compliance upgrades.
Executing an initial settlement or endorsing a partial draft forecloses your legal right to demand fair restitution. Every unquantified square foot of compromised framing or secondary wind penetration is paid straight out of your operating capital.
TRANSPARENT 3-STEP RECOVERY
Our 24-Hour
Forensic Audit
Demystifying insurance adjustments with institutional forensic methodology. Expedited turnaround, zero upfront capital, and no fee unless we win your settlement.
01
Initial Consultation
We examine your active insurance policy and initial settlement offers to identify immediate coverage gaps and missing line items.
Free Policy & Claim Review • NO Upfront Fees
02
Deep-Dive Inspection
Licensed forensic adjusters perform an exhaustive structural appraisal to uncover concealed hurricane and code-mandated damages.
On-Site Damage Inspection • Detailed Claim Documentation
03
Maximum Settlement
We substantiate all losses with rigorous forensic documentation, negotiating directly with carrier adjusters to secure every dollar owed.
NO Upfront Fees • 100% contingency basis
NO Upfront Fees • Retainer Fee Deducted Exclusively Upon Payout
VERIFIED FLORIDA SETTLEMENTS
Proof of Our Recent
Platinum Standard
Hard empirical evidence from recent Florida hurricane recovery audits. When insurers minimize structural payouts, our forensic accounting establishes legitimate replacement value.
COMMERCIAL PROPERTY
Commercial Property Settlement
INSURER INITIAL OFFER
$65,210
Initial carrier estimate
ACTUAL ENTITLEMENT
$716,388
Certified forensic recovery
+$651,178 RECOVERED (+998% DELTA)
Forensic structural audit identified extensive storm damages and code-mandated building compliance upgrades omitted by the insurer's adjusters.
RESIDENTIAL PROPERTY
Residential Storm Recovery
INSURER INITIAL OFFER
$16,745
Initial carrier assessment
ACTUAL ENTITLEMENT
$136,745
Certified forensic recovery
+$120,000 RECOVERED (+717% DELTA)
Forensic thermal imaging and moisture mapping proved catastrophic wind and envelope failure previously denied as routine wear and tear.
RESIDENTIAL PROPERTY
Residential Property Settlement
INSURER INITIAL OFFER
Below Deductible
Initial carrier assessment
ACTUAL ENTITLEMENT
$81,639
Certified forensic recovery
+$81,639 RECOVERED (DENIAL OVERTURNED)
Forensic documentation of concealed hurricane damage and Florida building code mandates overturned carrier's below-deductible denial.
RESIDENTIAL PROPERTY
Residential Windstorm Recovery
INSURER INITIAL OFFER
$11,379
Initial carrier assessment
ACTUAL ENTITLEMENT
$58,990
Certified forensic recovery
+$47,611 RECOVERED (+418% DELTA)
Forensic structural audit identified extensive wind damage and code-mandated repairs omitted by initial carrier adjuster.
STATUTORY ADVOCACY & FIDUCIARY COMMITMENT
NO Upfront Fees.
Absolute Transparency.
Under Florida Statute § 626.854, licensed public adjusters are the only independent damage valuation experts authorized to represent policyholders against commercial insurance carriers. Carrier adjusters owe a contractual duty to the insurer; Platinum Public Adjusters owes a fiduciary obligation solely to you.
We operate exclusively on a performance-contingent covenant: No Recovery, No Fee. You never pay out-of-pocket costs, upfront retainers, or engineering assessment invoices. Our statutory fee is capped by state regulations and is compensated solely as an agreed percentage from the newly recovered capital we capture from your insurer.
- Statutory Contingency Cap: Strictly compliant with Florida Department of Financial Services statutory ceilings.
- Fiduciary Claim Representation: Independent documentation that counters carrier-retained assessment shortcuts.
- Zero Financial Exposure: If we do not capture supplemental proceeds above your initial offer, you owe $0.
Florida Legal Safeguard
Every recovery claim is backed by formal contractual assurances: no retained rights over property settlements, no hidden admin fees.
24-HOUR FORENSIC RESPONSE GUARANTEE
Claim Your 24-Hour
Free Audit
Our licensed public adjusters review your Florida property damage file and policy limits within 24 hours. Zero cost to review, immediate actionable valuation.